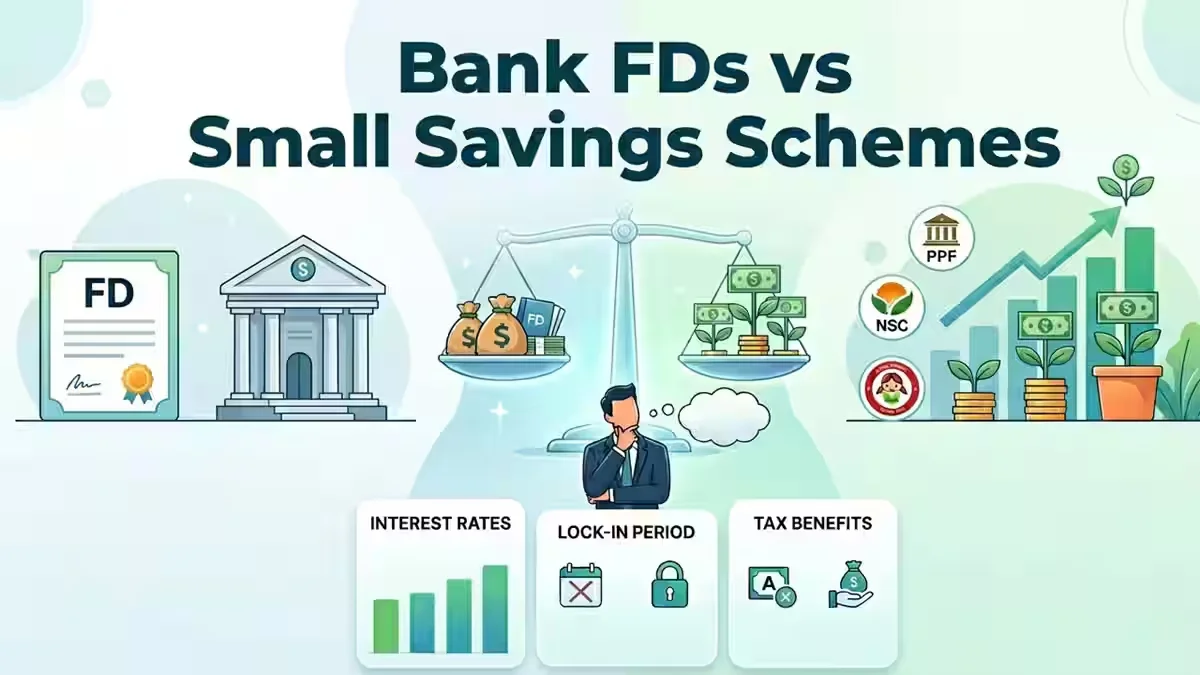
FD vs Small Savings Schemes 2026: When you think about your savings, one simple question often comes to mind: “Am I getting the best return for my money?” With prices rising and future expenses always around the corner, choosing the right place to invest has become more important than ever.
Many people still trust traditional options like bank fixed deposits, while others prefer government-backed schemes that promise slightly better returns. If you are also stuck between these two, this update will help you understand where your money can grow faster and more safely.

FD vs Small Savings Schemes 2026
| Feature | Bank Fixed Deposits (FDs) | Small Savings Schemes |
|---|---|---|
| Interest Rate | Around 6.25% to 6.66% | Up to 8.2% |
| Popular Options | State Bank of India, HDFC Bank, ICICI Bank | Sukanya Samriddhi Yojana, Public Provident Fund |
| Maximum Returns | Moderate returns | Higher returns |
| Safety | Safe with reputed banks | Backed by Government |
| Tax Benefits | Interest fully taxable | Tax deduction up to ₹1.5 lakh under 80C |
| Liquidity | High (easy withdrawal options) | Limited (lock-in period in most schemes) |
| Risk Level | Low | Very Low |
| Best For | Short-term savings and flexibility | Long-term wealth creation and tax saving |
Interest Rates in 2026: What Has Changed?
The Government of India has decided to keep interest rates on small savings schemes unchanged for the April to June 2026 quarter. Even without any increase, these schemes are still offering higher returns compared to most bank fixed deposits.
At present, bank FDs are offering interest rates in the range of about 6.25% to 6.66%. On the other hand, small savings schemes are going up to 8.2%, which clearly makes a noticeable difference over time.
Small Savings Schemes: Higher Returns with Government Support
Small savings schemes continue to attract investors who want both safety and better returns. Popular options like Sukanya Samriddhi Yojana are offering interest rates as high as 8.2%, making them one of the most rewarding choices right now.

Other schemes like Kisan Vikas Patra are offering around 7.5%, while the Post Office Monthly Income Scheme gives about 7.4%. The trusted Public Provident Fund continues to provide 7.1% returns.
Since these schemes are backed by the government, many investors feel more confident knowing their money is secure while still earning strong returns.
Bank Fixed Deposits: Stable and Easy to Access
Bank fixed deposits still remain a favorite for those who prefer simplicity and quick access to funds. Major banks like State Bank of India, HDFC Bank, and ICICI Bank are offering around 6.25% interest on FDs. Meanwhile, Kotak Mahindra Bank is offering about 6.50%, and Yes Bank is going up to 6.66%.

While these rates are slightly lower than small savings schemes, FDs offer flexibility. You can choose different tenures and even withdraw money when needed, which makes them useful for short-term planning.
Tax Benefits: Where You Save More
One of the biggest advantages of small savings schemes is tax benefits. Under Section 80C of the Income Tax Act, you can claim deductions of up to ₹1.5 lakh on your investment. In some schemes, even the interest earned is tax-free, which increases your real returns.
In contrast, the interest earned from bank FDs is fully taxable. This means that even if the rate looks attractive, your actual earnings may reduce after tax is applied.
Safety: Which Option Feels More Secure?
When it comes to safety, both options are considered reliable. Small savings schemes are backed by the government, which gives them a strong sense of security. At the same time, bank FDs are also safe, especially when invested in well-established banks. So, the real difference is not about safety but about returns, tax benefits, and flexibility.

FD or Small Savings: What Should You Choose?
Instead of choosing one over the other, many financial experts suggest balancing both. Bank FDs can help you manage short-term needs and liquidity, while small savings schemes can help you grow your wealth over time with better returns and tax savings. This way, you are not putting all your money in one place, and you get the best of both worlds.
Disclaimer: This article is for general informational purposes only and should not be considered financial advice. Interest rates and policies may change over time. Please consult a financial advisor or check official sources before making any investment decisions.
Also read:

Realme Narzo 100 Lite Launch: Price Features 7000mAh Battery 144Hz Display India
Build Big Retirement Corpus: Even on a Small Salary With Smart Saving Strategies